Weekly recap: the market rises, and one venue is all of it
Total volume rose 9.1% to $176.23M. Obiex added more than the whole market gained, so without it the week fell 2.5% — and deposits dropped 9.2% to the thinnest week since early September.
- 68.8%
- Obiex's share
- −2.5%
- The market without Obiex
- 184,039
- Deposits
- $256
- Average retail deposit
it added more than the market gained
against +9.1% with it
down 9.2%, thinnest since early September
up from $214
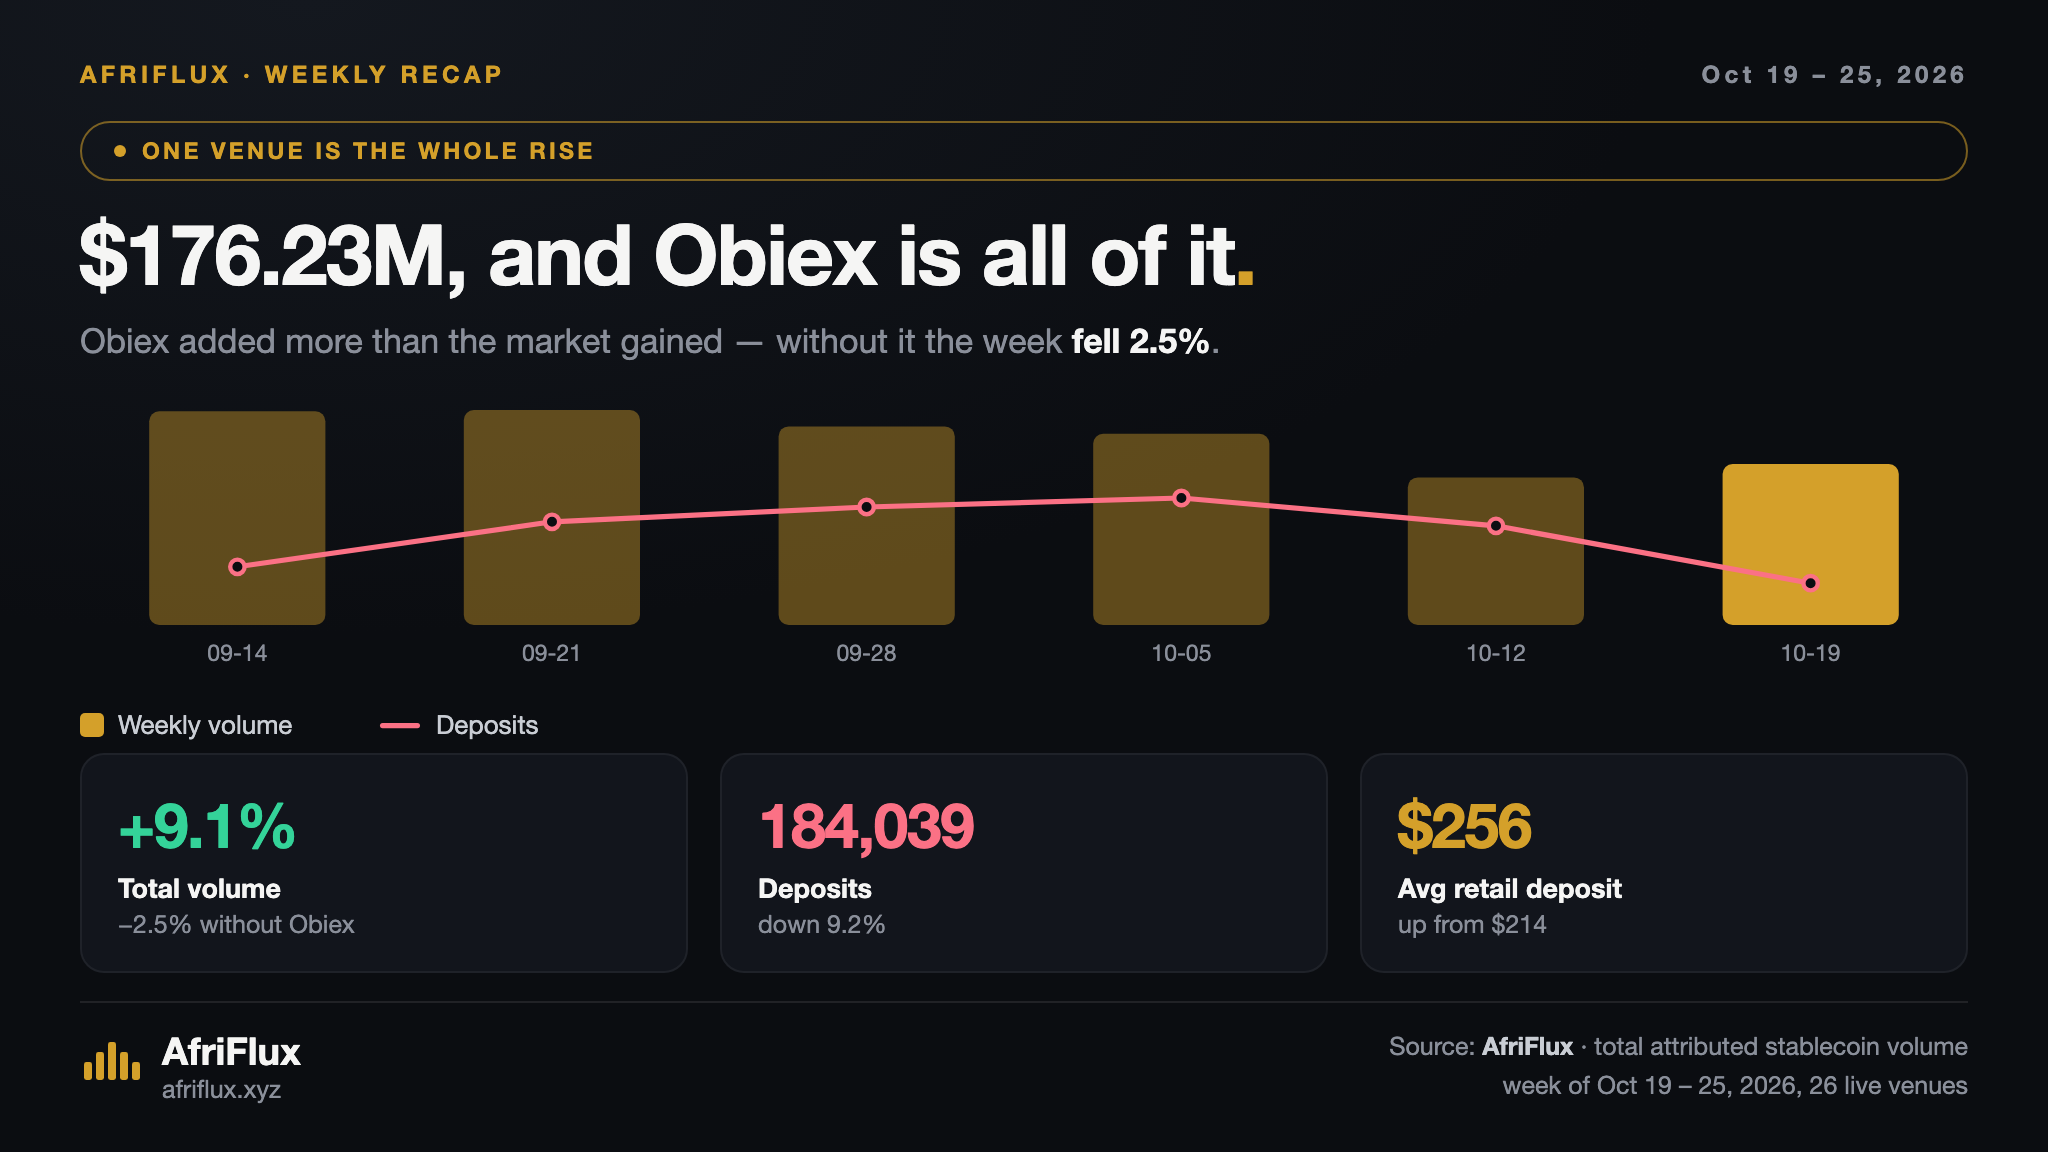
Total attributed stablecoin volume across the 26 venues we publish was $176,234,440 in the week of 19 to 25 October — up 9.1%.
The rise is one venue. Obiex added $16,173,635 while the market as a whole gained $14,743,537. Strip Obiex out and the week fell 2.5%, from $56,415,698 to $54,985,599.
Obiex, and everyone else
Obiex did $121,248,841, up 15.4%, and is 68.8% of everything we publish, against 65.1% the week before.
Underneath, the week was flat to soft. 13 of 25 venues grew and 12 fell. Quidax rose 12.5% to $14,019,141 and Luno rose 63.2% to $2,173,598 on a small base. Flutterwave fell 18.6% to $17,577,496, the largest absolute decline of the week at −$4,015,262. Raenest gave back most of the previous week's jump, down 63.6% to $234,924. Monica was flat at $4,510,755 and Spenda unchanged at $2,630,993.
Fewer deposits, bigger ones
Deposits fell 9.2% to 184,039 — the thinnest week since 7 September. Active wallets fell 2.9% to 58,873.
Yet the retail deposit book rose 8.7% to $47,067,886. The two move in opposite directions because the average retail deposit rose to $256, from $214 — up nearly a fifth in a week.
That is not an Obiex effect. Excluding it, the average still rose from $129 to $150, and deposits still fell 9.3%. Fewer people put money in last week, and the ones who did put in more.
The two-week shape
Last week the three largest books each fell about a quarter while the deposit base held. This week one of them recovered most of that, the base thinned, and the rest of the market drifted down.
Taken together, the eight-week series reads: $250.43M, $244.08M, $234.01M, $235.34M, $217.26M, $209.28M, $161.49M, $176.23M. The trend over two months is down; this week is a partial step back up inside it, and one venue is doing the stepping.
October so far
Through 25 October the month stands at $654,275,397, against September's $1,027,774,433 across the full month.
Six days remain. We publish October when October closes, and not before.
Method
Total attributed stablecoin volume across the 26 venues published as live, for the ISO week of 19–25 October 2026: each venue's observed flow, plus business books at venues that publish one separately, plus confirmed settlement into a venue's own sinks at venues whose books separate cleanly. At the two venues tagged customer_capped (Luno, VALR) the published figure is the per-client boxes under $1M lifetime only; boxes above that line are large enough to be a desk or market maker rather than a retail customer, so they are excluded here and disclosed separately — $249,462,661 in this week alone. Deposit-side only, so a rise in volume is a rise in money arriving, not in money held. Averages are the retail book over retail deposits, the same basis on both sides. The prior week restates from the $161,387,109 we published to $161,490,903 (+0.06%) and its deposit count from 201,474 to 202,771 (+0.6%), both ordinary attribution drift; percentage changes here are measured against the restated figures. Venues in mapping or terminal review are excluded.
How attribution works →Cite this
Free to cite with attribution. No embargo, no approval needed.
AfriFlux (2026). Weekly recap: the market rises, and one venue is all of it. Published 26 October 2026. https://www.afriflux.xyz/feed/weekly-recap-2026-w43
Reproducing a chart? Use this line: Source: AfriFlux — on-chain intelligence for Africa's stablecoin economy. afriflux.xyz